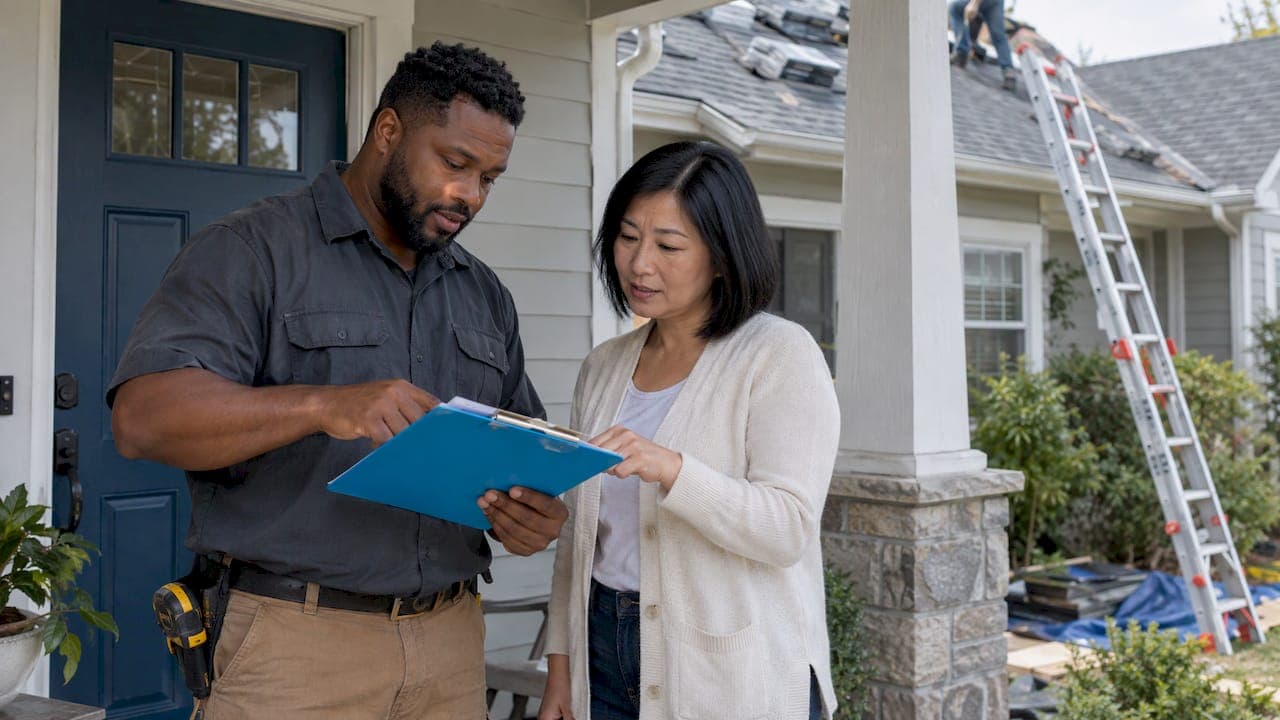
Roofing contractor insurance is a package of business policies that pays for injuries, property damage and equipment losses that come with working at height. Most roofers need general liability, workers' compensation if they have employees (and in some states even if they don't), and commercial auto. Larger jobs and some states add requirements on top. Below you will find what each policy does, what drives the price, how requirements differ by state, and how homeowners and developers can check a roofer's coverage before work starts.
TL;DR
- General liability is the core policy for a roofer. It pays for third-party injury and property damage, including problems that show up after a job is finished.
- Workers' compensation rules vary widely. California requires it of roofing licensees even with no employees, while Texas lets most private employers choose.
- Required limits depend on the state and the type of project. Oklahoma, for example, sets different minimums for residential and commercial roofing.
- Cost depends on payroll, the mix of work, claims history, limits and deductibles, so a quote from an agent who shops several carriers is the reliable way to price it.
- Homeowners and developers should verify the certificate of insurance and call the listed agent before the first shingle comes off.
Table of Contents
- What roofing contractor insurance covers
- What affects the cost
- Roofing insurance requirements by state
- Why additional insured status matters
- Homeowners and developers: how to check a roofer's insurance
- Our perspective
- Get your roofing coverage in order
- FAQ
- Sources
What roofing contractor insurance covers
Roofing is one of the riskiest trades to insure. Crews work at height, handle hot materials and heavy loads, and open up someone's home to the weather. One slip can mean a worker injury, a damaged ceiling or a lawsuit. Insurers price the trade accordingly, and many carriers will only write it through a policy built for roofing operations.
A complete program usually has several parts. Each one answers a different question: who gets hurt, what gets damaged, and who pays.
| Policy | What it generally pays for | Who it protects |
|---|---|---|
| General liability | Third-party bodily injury and property damage, including completed work | Customers, neighbors, the public |
| Workers' compensation | Medical care, lost wages, rehab and death benefits for work injuries | Your employees |
| Commercial auto | Crashes involving work trucks and vans | Your company vehicles |
| Commercial property or inland marine | Tools, equipment, and a shop or storage space | Your business assets |
| Business owner's policy (BOP) | General liability and property bundled together | Smaller operations |
| Professional liability (E&O) | Claims of faulty advice, estimates or design errors | Your business |
| Builders risk | The structure under construction or renovation | The project owner and contractor |
| Personal or commercial umbrella | Extra limits on top of underlying policies | Your balance sheet |
General liability
This is the first policy a roofer buys, and the one clients ask to see. It responds when your work injures someone who is not your employee or damages their property. Think of a dropped tool, a fire from a torch, or a leak that ruins a ceiling after you leave.
Limits matter as much as the headline. A common structure in construction is $1,000,000 per occurrence, $2,000,000 general aggregate and $2,000,000 products-completed operations aggregate. The same Colorado construction-risk presentation flags roof, residential, height-limit and subcontractor exclusions as items to review. That is why "we have $1 million of insurance" is an incomplete answer. Ask which limit it is, and what the policy excludes.
Workers' compensation
Workers' compensation generally pays medical costs, wage-loss or disability benefits, rehabilitation and death benefits after a work injury. As Wisconsin's insurance regulator explains, it applies to work-related injury or death and is not health insurance for non-work disability. For roofers, who work at height every day, it is usually the largest single line in the budget.

If you have employees, or you hire subcontractors who lack their own coverage, workers' comp is where cost surprises come from. Our guide to who must carry workers' comp coverage in 2026 walks through the rules in more detail.
Commercial auto, tools and equipment
A personal auto policy generally is not built for a truck loaded with ladders, tools and crew on the way to a job. Commercial auto covers vehicles used in the business. Commercial property and inland marine coverage protect tools, equipment and any shop or storage location against theft, fire and similar losses.
Umbrella and professional liability
When a claim exceeds the limits of a general liability or auto policy, an umbrella adds another layer. Professional liability (errors and omissions) addresses claims that your advice, estimate or specification was wrong. Both are worth discussing once you take on larger or commercial work.
What affects the cost
No honest article can give one price for a roofer, because the premium is built from your own business. These are the main factors carriers weigh:
- Payroll and headcount. Workers' comp is typically priced against payroll, so more crew means a larger premium.
- Type of work. Residential re-roofs, commercial flat roofs, hot tar and torch-down work are rated differently. Steep or tall roofs carry more risk.
- Subcontractor use. Uninsured subs can push their exposure onto your policy.
- Claims history and years in business. A clean record helps.
- Limits and deductibles. Higher limits cost more. A higher deductible lowers the premium but leaves you holding more of each loss.
- Revenue and location. Annual receipts and the state you work in change rates.
- Safety program. Written procedures, fall protection and training are things underwriters look for.
A bundle is often cheaper than buying every piece separately. Combining general liability and property in a BOP is a common way for smaller roofers to do that. Because we are an independent agency, we can compare carriers for you rather than quoting a single company's rate.
Roofing insurance requirements by state
There is no single national rule. States, counties and cities set their own, and clients and general contractors add contract requirements on top. A few examples show how different they are.
California
California requires employers, including construction employers, to carry workers' comp even with one employee. The state contractors board goes further for roofers: active C-39 roofing licensees must carry workers' compensation regardless of whether they have employees. You can satisfy the requirement with a valid certificate, authorized self-insurance or, where permitted, a signed no-employee exemption, but that exemption does not apply to the roofing classification.
Oklahoma
Oklahoma requires roofing registration before you offer or perform roofing work. The Construction Industries Board says residential registration requires at least $500,000 of general liability, while commercial roofing requires at least $1,000,000. The administrative rule adds details: the policy must specifically cover roofing, identify the firm and registration, and name the Construction Industries Board as certificate holder. It also calls for workers' comp or an authorized exemption for residential roofing, and workers' comp for commercial roofing.
The lesson: required limits can depend on the type of project, not just the size of your company.

Wisconsin
Wisconsin generally requires workers' comp when an employer has three or more full- or part-time employees, or one or more employees and at least $500 in combined gross wages in a calendar quarter.
Colorado
Rules are often local. The Pikes Peak Regional Building Department requires a current workers' comp certificate when a contractor has any employees. A business with no employees must provide a compliant rejection of coverage. Its general liability schedule uses $1,000,000 each occurrence and $2,000,000 aggregate for the listed building and single-trade categories.
Texas
Texas is unusual. The Roofing Contractors Association of Texas reported in March 2026 that most private employers are not required to carry workers' compensation, although contractors must follow notification rules and can choose to buy it. Even so, many commercial clients and general contractors require it by contract.
Contract requirements can exceed the law
Large commercial work often asks for far more than the state minimum. One New York subcontract appendix, for instance, requires workers' comp as required by law, $1,000,000 in employer liability limits, and at least $10,000,000 per occurrence for specified work when its risk provisions apply. If you bid on larger jobs, ask for the insurance exhibit early, so you can set up umbrella limits before the contract is signed.
Rules change. Before you register or bid, check the current requirements with your state licensing board and your city or county building department.
Why additional insured status matters
Clients, property owners and general contractors often ask to be listed as an additional insured on your general liability policy. That extends your policy's protection to them for claims arising from your work. It must be set up properly by endorsement, and the wording matters. Our explainer on additional insured status for contractors covers how it works and what to ask your agent for.
Homeowners and developers: how to check a roofer's insurance
If you are hiring a roofer, a certificate of insurance (COI) is your first line of defense, but only if you read it. Before work begins:
- Match the name. The legal business name on the certificate should be the company you are actually hiring.
- Look for both main policies. General liability and workers' compensation should both appear.
- Check dates and limits. The policy must be active through the whole project, and the limits should fit the job.
- Read the description of operations. Look for exclusions that affect your project.
- Call the listed agent. Confirm the coverage is active. A certificate alone does not prove it.
- Ask about additional insured status. Ask whether you can be added to the policy for the job.
These steps follow guidance on verifying a contractor's certificate of insurance. For a deeper look at what a missing or weak certificate can cost you, see this contractor insurance checklist for landlords.
If a roofer without workers' comp is injured on your property, you could face a claim. That is why we suggest that homeowners ask for proof of coverage before signing, and that you speak with your own home insurance agent if you have questions about how your policy responds.
Your own roof and your own policy
The roof also affects your homeowners policy. Material, age and condition all influence rates and coverage. We explain how in why roof type affects insurance rates and how roof condition affects premiums. If a new roof is coming, tell your agent afterward, because it may change what you pay.
Our perspective
Most roofers we talk with start by asking for the cheapest certificate. We understand why: margins are tight and clients want paperwork fast. But the policy that wins you jobs and the policy that protects you are only the same policy when the limits, exclusions and endorsements are right for your work.
That is where being independent helps. We are not tied to one carrier, so we can shop your general liability, workers' comp, commercial auto and equipment coverage together and match them to what you actually do: residential re-roofs, commercial flat roofs, or a mix. We also look at the contracts you sign, because a requirement for additional insured status or higher limits is much easier to handle before the bid than after it.
For homeowners and developers, our advice is simple: ask for the certificate, read it, and call the agent. A good roofer will not mind.
Mike
Get your roofing coverage in order
MF&T North America is an independent insurance agency in Arlington, MA, with more than 30 years of experience. We help contractors with general liability, workers' compensation, commercial property, commercial auto, business owner's policies and professional liability, and we work with clients in multiple states. You can see what we offer on our business insurance page.
If you are a developer or contractor with a project underway, we also write single-project and term policies through our builders risk insurance program. Licensed agents work with you directly, and we offer same-day binding on builders risk. Homeowners can start with our home insurance options.
FAQ
Do roofers need general liability insurance?
In most cases, yes, in practice. Some states and local licensing bodies set minimums, such as Oklahoma's $500,000 for residential and $1,000,000 for commercial roofing registration. Even where the law is silent, clients and general contractors commonly require it before you start work.
Do I need workers' comp if I work alone?
It depends on the state. California requires active roofing licensees to carry it regardless of whether they have employees. Other states, such as Wisconsin, set thresholds based on the number of employees or wages paid. Check with your state's regulator and ask your agent how your situation is treated.
How much does roofing contractor insurance cost?
It varies with payroll, type of roofing work, claims history, limits, deductibles and location. Workers' comp is usually the biggest piece for companies with a crew. We can compare carriers and quote the package for your specific business.
What should I look for on a roofer's certificate of insurance?
Check that the business name matches, that general liability and workers' comp are listed, and that the dates and limits fit your project. Read the description of operations, then call the listed agent to confirm the policy is active.
Sources
- Consumer's Guide to Insurance for Small Business Owners, Wisconsin Office of the Commissioner of Insurance
- The CGL Policy, COI's and Construction Risk Management, Colorado Bar Association
- Workers' Compensation Requirements, California Contractors State License Board
- Active Roofing Contractor Requirements, Oklahoma Construction Industries Board
- Okla. Admin. Code § 158:85-2-1, Registration, insurance
- Insurance Requirements for Contractors, Pikes Peak Regional Building Department
- Standard Insurance and Bonding Appendix, New York
- Roofing Contractors Association of Texas, workers' compensation news, March 2026
- How to Verify a Contractor's Certificate of Insurance
- Contractor Insurance Checklist for Landlords