Ordinance or law coverage pays the extra rebuilding cost that current building codes force on you after a covered loss, on top of what a standard policy pays for like-for-like repair. It comes in three parts, known as Coverage A, B, and C, and it's usually an optional endorsement rather than a built-in feature on most U.S. property policies. Skip it, and a partial loss on an older building can leave you covering thousands of dollars in code-mandated upgrades entirely out of pocket.
TL;DR:
- Coverage A pays for the value loss of undamaged building sections mandated for demolition when newer codes require it.
- Coverage B covers demolition and debris removal costs linked to code-mandated work separate from standard cleanup.
- Coverage C reimburses the increased construction costs needed for upgrades like fire safety, electrical wiring, or accessibility mandated by current codes.
- Claim triggers depend on actual enforcement, such as permit approval or damage exceeding 50% of the building's value, supported mainly by official building department documentation.
- Many older or historic buildings face higher code-upgrade risks, and reviewing coverage limits with a professional ensures proper protection before a loss occurs.
Table of Contents
- What Are the Three Parts of Ordinance or Law Coverage?
- What Actually Triggers an Ordinance or Law Claim?
- Do You Need Ordinance or Law Coverage?
- How Do You Document a Code-Driven Rebuild Claim?
- How Do You Check or Increase Your Coverage?
- What We See Most Often in Client Policies
- Get Your Ordinance or Law Coverage Reviewed the Right Way
- Useful Resources for Ordinance or Law Coverage
- Sources
- FAQ
What Are the Three Parts of Ordinance or Law Coverage?
Every ordinance or law endorsement breaks into three pieces, and knowing which is which matters when you're reading your declarations page or reviewing a contractor's estimate.
Coverage A pays for the loss in value to the undamaged portion of your building when local code requires you to demolish or alter parts that weren't actually damaged. If a fire destroys one wing of a building and code now requires the whole structure to be brought up to current standards, Coverage A address that undamaged section.
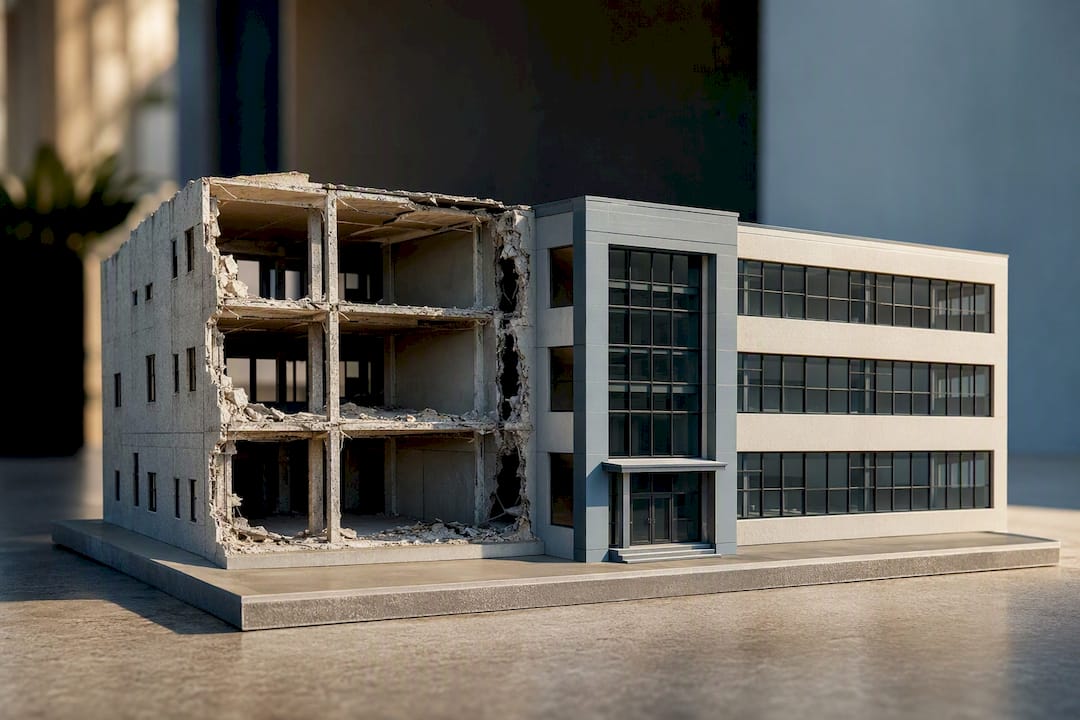
Coverage B covers demolition and debris removal costs tied to the code-required work, separate from the ordinary cleanup your standard policy already pays for.
Coverage C, usually the biggest number, pays the increased cost of construction. This is the money that covers upgrades your old building never needed until the code changed. Common examples include:
- Fire sprinkler systems in buildings that predate modern fire codes
- Full electrical re-wiring to meet current safety standards
- Egress windows and updated exit stairways
- Seismic or hurricane tie-down connectors in retrofit zones
- ADA-compliant accessible routes and restrooms
- Insulation, windows, and HVAC upgrades required by current energy codes
Demolition costs and the undamaged-portion value are treated as separate exposures from construction cost increases because they're driven by different mechanics: one is about tearing down what code no longer permits, the other is about what it costs to rebuild what remains to today's standard, as REI Prime's breakdown of the coverage explains.
What Actually Triggers an Ordinance or Law Claim?
A covered loss by itself doesn't open the door to an ordinance or law payout. Coverage only activates when a civil authority actually enforces a code requirement tied to that loss, and that distinction trips up more claimants than any other part of this coverage.
Two enforcement paths show up most often:
- Permit-triggered review. When you apply for a repair permit, the building department reviews the scope and can require code upgrades as a condition of approval, even on a relatively small repair.
- Substantial-damage thresholds. Many jurisdictions apply a percentage test, commonly known as the "50% rule," where damage equal to or exceeding half the building's value triggers a full code compliance review rather than a simple repair.
The exact threshold and enforcement method vary by city and county, which is why IRMI's commentary on ordinance and law disputes points to documentation, not policy wording, as the real deciding factor in most claims. The written proof insurers accept usually includes a building-department determination letter, formal permit conditions citing specific code sections, and any correspondence establishing that the upgrade is a legal requirement rather than a preference.
Statistic to remember: insurers and adjusters weigh the written building-department determination far more heavily than an unsupported contractor estimate, according to IRMI's analysis of how these disputes actually resolve.
Do You Need Ordinance or Law Coverage?
If your building was built before the 1990s, has any nonconforming features, or carries historic designation, you're carrying more code-upgrade risk than you probably realize. The same goes for multifamily buildings, commercial properties, and any structure where a lender or federal program has flagged rehabilitation requirements. Some lenders and programs, including certain Fannie Mae and HUD-backed transactions, actually require ordinance or law coverage as a condition of financing on nonconforming properties, which turns this from a claims question into an underwriting one.
Endorsement limits are typically expressed as a percentage of your dwelling coverage, and the three most common options are:
- Limits often come as percentages of your dwelling coverage. Common tiers exist for different building ages and conditions, ranging from lower percentages for newer construction with minimal code gaps to higher percentages for older, historic, or heavily nonconforming structures where significant code upgrades may be required.
The wider the gap between your building's original construction and today's code, the more likely Coverage C becomes your largest exposure, and sizing should reflect that.
Ask specifically how much of that percentage applies to construction cost increases, since that's usually where the real money is.*
How Do You Document a Code-Driven Rebuild Claim?
Claims succeed or fail on paperwork, not persuasion. The strongest ordinance or law claims share the same pattern: a documented, code-specific trail connecting the loss to the required upgrade.
- Request a written determination or permit conditions letter from the building department that cites the exact code sections triggering the upgrade
- Have your contractor produce a separated, line-item estimate that isolates code-upgrade costs from standard repair costs
- Keep records of your building's pre-loss condition, including any known nonconforming features
- Preserve any prior correspondence with the building department, especially anything referencing planned or required upgrades
As one industry analysis of these disputes puts it:
When preparing a claim for ordinance-or-law coverage, separate the code-driven scope line-by-line and tie each line item to the specific code citation in the building-department communication. This minimizes disputes and speeds adjustments.
That advice comes from IRMI's technical guidance on documentation strategy, and it holds true whether you're rebuilding a single-family home or a commercial retail space. A contractor's estimate alone, without that written code citation, tends to carry little weight in a dispute.
How Do You Check or Increase Your Coverage?
Your declarations page will list the ordinance or law endorsement as a percentage of your dwelling or building limit, or as a scheduled dollar amount for each of Coverage A, B, and C separately. Commercial and builders risk policies frequently schedule B and C as flat dollar figures rather than percentages, according to Rimkus's overview of building code upgrade coverage, so don't assume your homeowners policy and your commercial policy work the same way.
When you're ready to review your coverage, ask your agent these three questions:
- Are Coverage A, B, and C all included, or is one component missing entirely?
- Are there separate sub-limits within the endorsement, and what's the actual dollar cap on Coverage C?
- Is the limit a percentage of my dwelling coverage, or a fixed scheduled amount?
If your building is older, historic, or you're planning a major renovation, a condition assessment or builder's cost estimate is worth ordering before you set your limit. A quick review of your home insurance for common coverage gaps is a good place to start.
What We See Most Often in Client Policies
The most common gap isn't a missing endorsement. It's a small built-in allowance, often a few thousand dollars, that a property owner assumes is real ordinance or law protection. It rarely covers even a fraction of what a code compliance review actually demands.
We also see headline percentages that look generous until you check the sub-limits and realize Coverage C, the piece that usually costs the most, is capped far below the stated percentage. An independent review at underwriting or renewal catches these gaps before a loss forces the issue, which is the entire point of having someone look at the declarations page who isn't the one who sold you the policy.
— Mike
Get Your Ordinance or Law Coverage Reviewed the Right Way
An independent insurance agency shops your ordinance or law coverage across multiple carriers instead of pitching whatever one insurer happens to offer, which means you get a sizing recommendation built around your actual building, not a generic percentage.
Whether you own a decades-old single-family home, manage a commercial property, or you're mid-renovation on a project that needs builders risk protection, our licensed agents review your declarations page, check how your Coverage A, B, and C sub-limits actually stack up, and recommend an endorsement percentage that matches your building's real code-upgrade exposure. Builders risk clients can get same-day binding on single-project and reporting-form policies, so a coverage gap doesn't stall a construction schedule.
If you're not sure whether your current policy has adequate protection, request a home insurance policy review or a business insurance quote today, and we'll walk through your ordinance or law limits line by line.
Useful Resources for Ordinance or Law Coverage
- IRMI: why documentation decides most ordinance and law disputes
- REI Prime: the ordinance or law coverage glossary
- Rimkus: building code upgrade coverage explained
- Massachusetts Board of Building Regulations and Standards
Sources
- Ordinance and Law Coverage: Why Documentation, Not Policy Language, Decides Most Disputes | IRMI
- Ordinance or Law Coverage: The Code-Upgrade Gap | REI Prime
- Building code upgrade coverage (Rimkus)
- Code upgrade coverage (PeriLiq)
- Mass
FAQ
Should I Get Ordinance or Law Coverage?
If your building was built before the 1990s, has any nonconforming features, or sits in a jurisdiction with active code updates, this coverage is worth adding. Many homeowners carry only a small built-in allowance rather than a real endorsement, and raising the limit is often inexpensive relative to the potential code-upgrade costs you'd otherwise pay yourself.
What Does the Ordinance or Law Coverage Endorsement Cover?
It covers three things: the value lost on the undamaged portion of your building when code forces demolition of parts that weren't damaged, the cost of that demolition and debris removal, and the increased cost of construction to meet current code. These are known as Coverage A, B, and C.
What Are the Four Types of Coverage?
Ordinance or law coverage itself is generally described as having three components (A, B, and C), not four. If you've seen "four types" referenced elsewhere, it's likely conflating a specific carrier's endorsement structure with the standard A/B/C framework, so confirm the breakdown directly on your declarations page.
Is an Ordinance a Law or a Policy?
An ordinance is a local law, typically passed by a city or county government, and building codes are usually adopted through this kind of ordinance. That's why the coverage is called "ordinance or law": it responds to legal requirements imposed by any level of government, not just a specific type of regulation.