A waiver of subrogation is a promise your insurer makes to give up its right to chase a third party for money it paid out on your claim. The immediate effect: your carrier absorbs the loss instead of suing the other party, even when that party caused the damage. You'll run into this most often in construction contracts and commercial leases, where the parties want to avoid lawsuits between people who need to keep working together.
TL;DR:
- A waiver of subrogation prevents your insurer from pursuing third parties to recover paid claims, often used in construction and lease agreements to avoid litigation.
- To ensure coverage, the waiver must be explicitly included as an endorsement on your insurance policy, not just a contractual promise.
- Cost for a waiver endorsement typically ranges from $100 to $300, depending on scope, industry, and claims history, and is generally cheaper than legal expenses from a subrogation lawsuit.
- Signing a waiver without confirming the endorsement is in place exposes you to coverage gaps, especially if the waiver is requested after a loss or in a jurisdiction with workers' compensation restrictions.
- The most reliable process involves requesting the endorsement through your agent, verifying its addition, and obtaining a Certificates of Insurance referencing the specific endorsement form.
Table of Contents
- What Is a Waiver of Subrogation, and Why Does It Exist?
- Contract Clause vs. Policy Endorsement: The Two Forms That Matter
- Where U.S. Contracts Commonly Demand a Waiver
- How to Actually Get an Endorsement Added to Your Policy
- What a Waiver of Subrogation Endorsement Actually Costs
- Mistakes That Turn a Waiver Into a Coverage Fight
- Sample Clause Language You Can Bring to Your Agent
- Agent Checklist: How to Comply Without Risking Your Coverage
- An Agent's View on the Mistakes That Cause the Most Trouble
- How M F and T North America Helps You Get This Right
- Sources
- FAQ
What Is a Waiver of Subrogation, and Why Does It Exist?
Subrogation is the legal mechanism that lets your insurer "step into your shoes" after paying a claim, then sue whoever actually caused the loss to recover the money, as explained in detail in medical insurance subrogation. It's how insurance companies keep premiums lower across the board. Without it, every driver, landlord, and contractor would absorb the full cost of other people's mistakes.
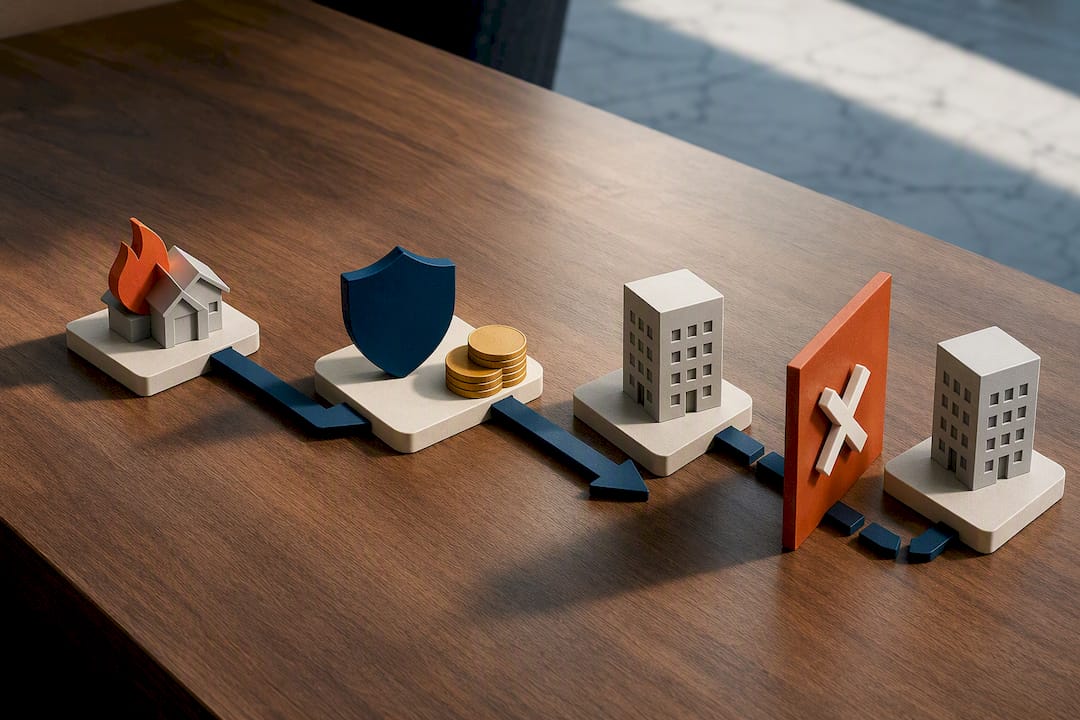
A waiver of subrogation shuts that recovery path down before it opens. Your insurer pays your claim as usual, but agrees in advance not to pursue the third party named in the waiver, even if that party's negligence caused the loss.
Businesses ask for these waivers for practical reasons, not legal cleverness:
- Avoiding lawsuits between parties who have to keep working together (a general contractor and a subcontractor, a landlord and a tenant)
- Speeding up claims resolution since nobody has to wait on a separate liability fight
- Protecting long-term business relationships that a subrogation suit would poison
- Meeting a contract requirement before work can even start
Contract Clause vs. Policy Endorsement: The Two Forms That Matter
A waiver written into a contract only binds the parties who signed it. It does not bind your insurance company unless a matching endorsement sits on the actual policy. This is the single most misunderstood part of the whole topic, and it's where a lot of businesses get burned.
LegalClarity notes there are two distinct mechanisms at play:
- The contract clause: language in your lease, construction contract, or vendor agreement that obligates you to obtain a waiver
- The policy endorsement: the actual form added to your insurance policy, such as ISO CG 24 04 for general liability or ISO WC 00 03 13 for workers' compensation
The gap between these two is where coverage disputes live. Sign a contract promising a waiver, skip the endorsement, and your insurer can still pursue subrogation, leaving you in breach of contract with no coverage to back you up.
Where U.S. Contracts Commonly Demand a Waiver
Four settings account for most of the waiver requests you'll ever see, and each has its own wrinkle.
- Construction projects. Owners, general contractors, and subcontractors typically exchange mutual waivers so a jobsite accident doesn't turn into a chain of lawsuits between people who need to finish the building together. The AIA A201 general conditions document has built mutual waiver language into standard construction practice for decades.
- Commercial leases. Landlords and tenants often waive subrogation rights against each other so a kitchen fire in one tenant's unit doesn't spark a lawsuit against the building owner or vice versa.
- Vendor, rental, and event contracts. A venue or equipment renter frequently requires a waiver before letting a caterer, contractor, or promoter onto the property.
- Workers' compensation. This one comes with real teeth. Several states restrict or flatly prohibit workers' comp subrogation waivers, and the rules vary by jurisdiction. Check your state's workers' compensation agency and the Department of Labor's OWCP guidance before assuming a waiver will hold up.
How to Actually Get an Endorsement Added to Your Policy
Getting a waiver of subrogation endorsement on your policy is mostly a paperwork sequence, but skipping a step is how businesses end up signing contracts they can't back.
- Pull the exact contract language. Get the full legal name and address of the party you need to protect. Underwriters will not guess at this.
- Send the request to your agent or broker. Underwriting reviews the request, checks whether the endorsement is available for your policy type, and prices it.
- Confirm whether you need a scheduled or blanket endorsement. A scheduled waiver names a specific party for a specific project. A blanket waiver covers any party you're contractually required to waive rights against, which costs more but saves you from resubmitting every job.
- Get the endorsement added to the policy, then request a Certificate of Insurance that specifically references that endorsement form number.
- If the carrier declines, you have three real options: renegotiate the contract language, shop for a carrier that will write the endorsement, or get the refusal in writing so you have a paper trail if the other party pushes back.
Pro Tip: A Certificate of Insurance is a snapshot, not proof of a waiver. The endorsement itself is the legal instrument, so ask your agent for the actual endorsement page, not just a COI that mentions it.
What a Waiver of Subrogation Endorsement Actually Costs
Endorsement fees run modest compared to what a subrogation lawsuit would cost either side. Scheduled endorsements, which name one specific party for one specific job, usually run $100 to $300. Blanket endorsements cost more since they extend coverage automatically to any party a contract requires.
Underwriters weigh a few factors before pricing the request:
- Your industry and claims history
- The policy's overall limits and how much exposure the waiver touches
- The scope of the contract, meaning how many projects or parties fall under the waiver
Compared to the legal fees and lost time a subrogation dispute drags on for, a few hundred dollars for an endorsement is usually the cheaper problem to have.
Mistakes That Turn a Waiver Into a Coverage Fight
The biggest risk isn't the waiver itself. It's signing one without confirming your insurer actually agreed to it.
- Signing a contract waiver with no matching endorsement leaves you personally exposed if your insurer pursues subrogation anyway, since the contract clause never bound the carrier.
- Requesting a waiver after a loss already happened rarely works. Post-loss waivers are typically ineffective and can violate the conditions of your existing policy.
- Assuming workers' comp waivers work like general liability waivers. They don't. Some states bar them outright, and your carrier may refuse regardless of what the contract says.
Confirm timing and state rules with your agent before you sign anything, not after a claim lands on your desk.
Sample Clause Language You Can Bring to Your Agent
A one-way waiver protects only one party. A mutual waiver protects both, which is standard on most construction jobs. Here's roughly what each looks like:
- One-way sample: "Contractor waives all rights of recovery against Owner and Owner's insurers for loss or damage to Contractor's property, to the extent covered by insurance."
- Mutual sample: "Owner and Contractor each waive all rights of recovery against the other for loss or damage to their respective property, to the extent such loss is covered by property insurance, and shall require their insurers to include a corresponding waiver of subrogation endorsement."
Check the mutual version for three things: named parties matching your contract exactly, a scope limited to insured losses (not all losses), and explicit reference to obtaining a matching endorsement. That last line is what pushes the clause from a paper promise into something your carrier will actually honor.
Agent Checklist: How to Comply Without Risking Your Coverage
Working through this with an agent is faster than guessing at it alone, and it protects you from signing a contract obligation your insurer never agreed to.
- Collect the contract's insurance requirements and the exact legal name of the party requesting the waiver.
- Ask your agent to confirm endorsement availability in writing before you sign anything with a waiver clause in it.
- Get the endorsement added to the policy, then request a Certificate of Insurance that cites the specific endorsement form.
- If your carrier denies the request, get that denial in writing and go back to the contract to renegotiate the waiver language.
Pro Tip: Start this process the week you receive the contract, not the week before the project starts. Underwriting turnaround on endorsements can take longer than most deadlines allow.
An Agent's View on the Mistakes That Cause the Most Trouble
Most waiver problems come from timing, not law. Requests arrive days before a signing deadline, forcing rushed decisions. A COI is not proof of an endorsement, so always ask to see the form itself. Paying a small fee upfront almost always beats the cost of a coverage dispute later.
— Mike
How M F and T North America Helps You Get This Right
Chasing down endorsement language on your own eats time you don't have, especially with a contract deadline breathing down your neck. An insurance agency reviews the waiver language in your contract, requests the specific endorsement from the carrier, and verifies the Certificate of Insurance actually matches what got approved, work that a lot of businesses try to handle themselves and end up redoing.
Whether you're a contractor juggling subcontractor agreements, a landlord negotiating a commercial lease, or a small business owner staring down a vendor contract, the fastest path forward is getting your commercial insurance reviewed before you sign anything. Request a quote and have an agent confirm exactly what endorsement your contract requires, before the deadline forces your hand.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
FAQ
Is a Waiver of Subrogation Always Required?
No. It's only required when a contract, lease, or vendor agreement specifically demands it, most often in construction, commercial real estate, and vendor arrangements.
What Are the Two Types of Waiver of Subrogation?
The first is a contract clause that binds the signing parties. The second is a policy endorsement, such as ISO CG 24 04, that binds the insurance carrier itself.
How Do You Get a Waiver of Subrogation?
You request it through your agent or broker, who submits it to underwriting for review and pricing, then confirms the endorsement is added to your policy before you sign the underlying contract.
Who Can Execute a Waiver of Subrogation?
The named policyholder or an authorized representative, working through their insurance agent, requests the endorsement; the insurance carrier's underwriter is the one who ultimately approves and issues it.
What's the Difference Between a Waiver of Subrogation and a Hold Harmless Agreement?
A waiver of subrogation stops your insurer from suing a third party after paying a claim. A hold harmless agreement shifts liability for future claims between the contracting parties directly, which is a separate legal tool often used alongside a waiver, not instead of one.