Completed operations coverage pays for third-party bodily injury or property damage caused by your finished work or sold product after the job is done or the sale is final. It matters most to contractors, manufacturers, installers, and service providers whose work keeps creating risk long after they've left the job site. Check your CGL or BOP policy today for the products-completed operations aggregate, the each-occurrence limit, and any contract language that spells out how long that coverage has to stay in force.
TL;DR:
- Completed operations coverage applies only to third-party bodily injury or property damage that occurs after the work is finished and not on-site.
- The coverage is triggered by different completion tests, with timing depending on whether the work is considered finished by contract, acceptance, or abandonment, and only if the damage occurs during the policy period.
- The products-completed operations aggregate is separate from the general aggregate, which means claims can exhaust one limit without affecting the other, potentially leaving higher risks unprotected.
- Many small contractors assume coverage extends indefinitely, but in reality, liability lasts up to the statute of repose, often around 10 years, unless extended reporting periods or umbrella policies are in place.
- Contractors should verify their policy limits, endorsement language, and coverage wording, especially in additional insured endorsements, because certificates alone may not reflect actual contractual coverage requirements.
Table of Contents
- What Completed Operations Coverage Actually Pays For
- When Coverage Triggers: Completion Tests and Policy Periods
- Understanding Your Products-Completed Operations Aggregate
- Exclusions and the Misconception That Costs Contractors Money
- Contract Language and Additional Insured Requirements You'll Be Asked to Sign
- How Long the Exposure Really Lasts
- Step-by-Step: Confirming You're Properly Covered
- Why This Guidance Comes From MF&T North America
- The Real Gap in How Contractors Think About This Coverage
- Get Your Completed Operations Coverage Reviewed
- Sources
- FAQ
What Completed Operations Coverage Actually Pays For
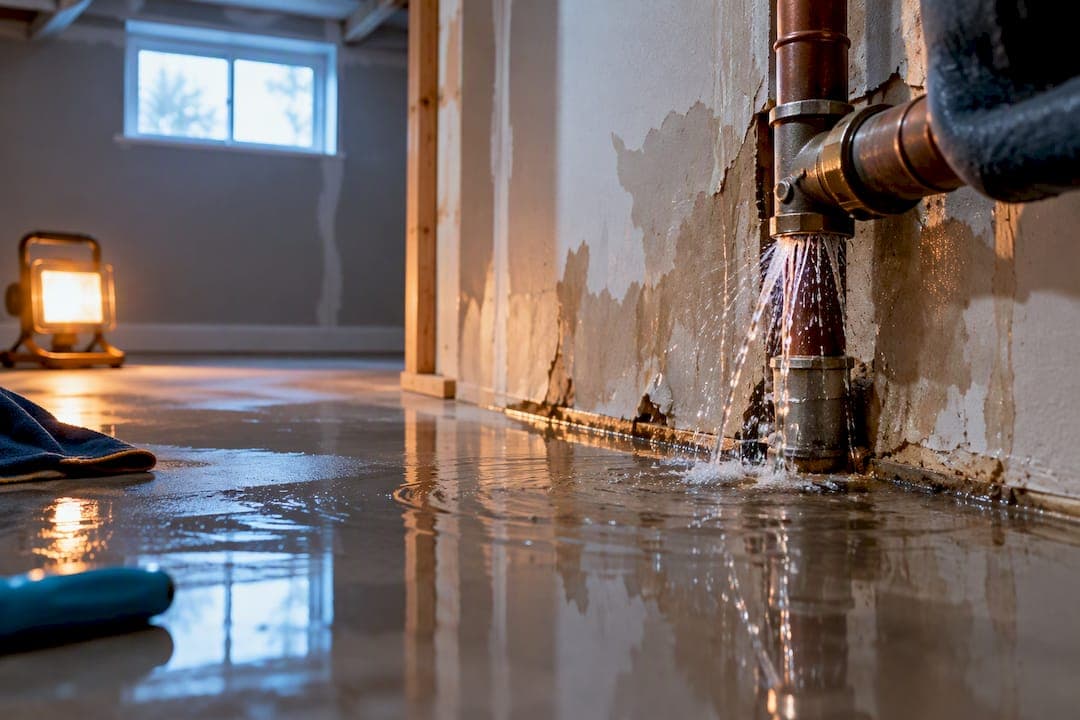
Picture a plumber who finishes a water heater install, and six weeks later a fitting fails, flooding the client's basement. That's a classic completed operations claim: the work was finished, the plumber was off-site, and the damage happened afterward on someone else's property. A manufacturer faces the same exposure when a part it sold two years ago causes an injury during normal use. A subcontractor's finished electrical work that later sparks a fire in an adjacent unit falls into the same bucket.
The common thread is the "away from premises" requirement. If a worker is still on-site and drops a tool on a client's floor, that's usually a premises or operations claim, not completed operations. The distinction matters because it can determine which aggregate limit a claim draws against.
Products and completed operations coverage responds to two things only:
- Bodily injury or property damage suffered by someone else
- Legal defense costs tied to that third-party claim
It will not pay to redo your own defective installation or replace a faulty product you sold, a point Procore's contractor guide makes explicit.
When Coverage Triggers: Completion Tests and Policy Periods
Insurers define "completed" a few specific ways, and the wording in your policy decides which one applies to you.
- Contract completion. Work is considered done when you finish everything specified in the contract, even on a multi-part job.
- Turnover or acceptance. Coverage can also trigger once the owner or another contractor takes over and starts using the space or product.
- Abandonment. If a project stalls and is never finished, most CGL forms still treat that unfinished portion as "completed" for liability purposes.
The bigger trap is timing. Standard occurrence policies pay only if the injury or damage happens during the policy period in force at that time, not the period active when you did the work. IRMI's coverage analysis is blunt about this: cancel your policy, and a claim that surfaces later has nowhere to go unless you've secured other protection. That's why the difference between claims-made and occurrence-based policies is not a technicality. It decides whether you need an extended reporting period, or a tail, to protect yourself after you close a policy.
Understanding Your Products-Completed Operations Aggregate
Here's the number that trips up more small business owners than any other in a CGL policy: your products-completed operations aggregate is a completely separate bucket of money from your general aggregate.
Pro Tip: Say your policy carries a $1 million each-occurrence limit, a $2 million general aggregate, and a $2 million products-completed operations aggregate. A completed-operations claim that pays out $500,000 does not touch your general aggregate at all. You still have the full $2 million available for premises and operations claims that happen the same year.
IRMI explains that this separation means your real total exposure capacity in a policy period is effectively the sum of both aggregates, not one shared pot. Most general contractors ask subcontractors for at least typical each-occurrence and aggregate limits, but higher-risk trades and manufacturers with significant product exposure often carry more. When project size or client contracts demand higher numbers than your CGL provides, an umbrella or excess policy adds capacity without rewriting your base coverage.

Exclusions and the Misconception That Costs Contractors Money
Completed operations coverage has real limits, and knowing them saves you from assuming you're protected when you're not.
- Damage to your own work or product, which is a warranty issue, not a liability one
- Product recall expenses, which need a separate recall policy
- Employee injuries, which belong under workers' compensation
- Auto-related incidents, which require commercial auto coverage
- Intentional acts and pollution incidents, unless you've added a specific endorsement
The misconception IRMI flags most often is the belief that coverage depends on when the work was performed rather than when the injury occurred. Business owners assume the policy active during the job automatically covers whatever goes wrong later. It doesn't. If your product causes a professional service failure instead of a physical injury, that's a job for professional liability insurance, not general liability coverage.
Contract Language and Additional Insured Requirements You'll Be Asked to Sign
General contractors and property owners rarely accept a certificate of insurance at face value anymore. They want specific language, and knowing what they're looking for before you sign saves you a scramble later.
- Minimum each-occurrence and PCO aggregate limits spelled out by dollar amount, often per project rather than blanket across your whole book of business
- Additional insured status naming the owner or GC for both ongoing and completed operations, not just while the job is active
- A continuation clause requiring you to maintain completed operations coverage for a set period after the work wraps, commonly one year, a pattern reflected in contract insurance templates used across the country
Some contracts also reference specific ISO endorsements, like a CG 24 07-style form, that redefine what falls under the products-completed operations hazard. Don't take a broker's word that you're covered. Read the actual endorsement page, since contractual liability language can shift coverage in ways a certificate alone won't show.
How Long the Exposure Really Lasts
Your liability doesn't expire when the invoice gets paid. State statutes of repose set the outer boundary for how long someone can sue you over completed work, and Procore notes that number commonly runs up to 10 years, though it varies by state and by the type of defect claimed.
- If you're on a claims-made policy, ask about an extended reporting period before you cancel or switch carriers, since a tail preserves your ability to report claims tied to past work
- Occurrence policies don't need a tail in the same way, but only the policy active when the injury actually occurs will respond
- Raising your products-completed operations aggregate through an umbrella or excess policy gives you more room if a large claim surfaces years after a project closes
Step-by-Step: Confirming You're Properly Covered
Don't wait for a claim to find out what your policy actually says.
- Pull your CGL or BOP declarations page and locate the products-completed operations aggregate line item.
- Confirm your each-occurrence limit and verify that your PCO aggregate is listed separately from your general aggregate.
- Ask your agent whether additional insured endorsements on file include completed operations, not just ongoing operations.
- Ask whether an extended reporting period is available if you're on a claims-made form, and what it would cost.
- Request the actual endorsement pages, not just a certificate of insurance, when a client or general contractor requires proof of coverage.
Pro Tip: A certificate of insurance is a summary, not proof of specific wording. IRMI recommends collecting the endorsement pages themselves whenever contract compliance hinges on exact PCO language, because a certificate can look fine while the underlying form says something different.
Why This Guidance Comes From MF&T North America
Insurance agencies with long experience placing commercial coverage for contractors, manufacturers, and small business owners across multiple states often encounter these questions during policy reviews. Such agencies typically help clients read endorsement wording line by line, confirm certificates match actual contract requirements, and set limits that fit the size of the jobs they bid on. Some blogs cover the claims-made versus occurrence distinction and explain additional insured status in plain language.
The Real Gap in How Contractors Think About This Coverage
Most advice on completed operations coverage focuses on whether you have it at all. That's the wrong starting point. Nearly every CGL policy sold to a contractor already includes some form of products-completed operations coverage. The real gap is between having the coverage and having the right limits and endorsement wording for the contracts you're actually signing.

I'd argue the single most overlooked failure point isn't the coverage itself. It's contractors treating the certificate of insurance as the finish line, when the general contractor or property owner actually cares about the endorsement pages behind it. A certificate can say all the right things while the policy underneath excludes exactly the scenario that ends up in a lawsuit three years later.
If you take one thing from this guide, prioritize the aggregate structure over the premium. A cheaper policy with a thin products-completed operations aggregate can leave you exposed on a single bad claim, especially in trades where injuries or property damage show up long after the invoice is paid. Match your limits to your actual project size and contract requirements, not to whatever number felt affordable at renewal time.
— Mike
Get Your Completed Operations Coverage Reviewed
If you're not sure whether your current policy's products-completed operations aggregate and endorsement language match your contracts, an insurance agent can review your declarations page and flag any gaps before a claim arises.
As an independent agency, MF&T North America isn't tied to one carrier's forms or limits, which means the review focuses on what actually fits your risk instead of what one insurer happens to sell. That's the practical advantage of working with an independent shop over sticking with whatever policy you were handed at startup: you get options compared side by side, not a single renewal notice. Whether you need a CGL and umbrella combination reviewed, a Business Insurance quote for a growing crew, or a Builders Risk policy for a single project, the next step is simple. Send over your current declarations and endorsement pages, and MF&T will tell you exactly where your products-completed operations aggregate stands and whether your additional insured wording actually covers completed operations. Request a quote and get that answer this week.
Sources
For deeper reading, see IRMI's CGL limits analysis, NAIC's classification notes, and Procore's contractor guide.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
- The Hazards of Products and Completed Operations: Understanding the Fundamentals
- Completed Operations: A Contractor’s Guide to Coverage, Cost, & More
- Insurance requirements for contracts and agreements — template (Sonoma County)
- Products-completed operations hazard endorsement (IIAT / sample CG form)
FAQ
What Does Completed Operations Coverage Cover?
It covers third-party bodily injury or property damage caused by your finished work or sold product, plus your legal defense costs for that claim. It does not pay to fix your own defective work, which Procore's guide clarifies is a warranty issue rather than a liability one.
How Long Does Completed Operations Coverage Last?
Practical exposure often runs as long as your state's statute of repose allows, which industry guidance commonly cites as up to 10 years depending on the state and the defect claimed. Your actual protection lasts only as long as you keep an active policy or secure an extended reporting period if you switch to claims-made coverage.
What Are the Four Types of Coverage in a Standard CGL Policy?
A standard commercial general liability policy generally addresses premises and operations liability, products and completed operations liability, personal and advertising injury liability, and medical payments coverage. Each responds to a different type of exposure, and completed operations specifically covers injuries or damage that occur after your work is finished and you've left the site.
What Does General Liability Cover for Contractors?
General liability covers bodily injury and property damage claims from third parties tied to your business operations, both while you're actively working and after the job is complete. MF&T North America helps contractors confirm that their general liability coverage actually includes the products-completed operations aggregate limits their contracts require, not just a bare-minimum policy.